SpaceX Earnings Surge Drives Analysts to Raise Price Targets Amid AI Expansion
A record-breaking third quarter and aggressive AI infrastructure spending prompted a widespread upward revision of stock valuations across Wall Street.
By Thabo Mokoena ·
SpaceX shares surged in premarket trading on Tuesday after the company reported a third-quarter performance that significantly outpaced Wall Street expectations, triggering a wave of price target upgrades from major investment firms. The stock, which closed at $147.79 on Monday, October 20, climbed approximately 8 percent in early Tuesday sessions as investors processed the financial results and the newly elevated forecasts.
The core of the bullish reaction stems from a massive jump in revenue and profitability. The company posted $14.6 billion in revenue for the third quarter, a 161 percent increase year-over-year that comfortably exceeded the consensus estimate of roughly $12.7 billion. This top-line growth translated into a net profit of $4.4 billion, reversing a prior-year loss, while adjusted EBITDA reached $8.8 billion. The surge was largely driven by the Super Intelligence division, which generated approximately $7.6 billion in revenue—a nearly 830 percent year-over-year increase—making it the largest revenue contributor. The Connectivity segment also performed strongly, delivering $5.2 billion in revenue as the Starlink consumer base expanded to 13.6 million subscribers.
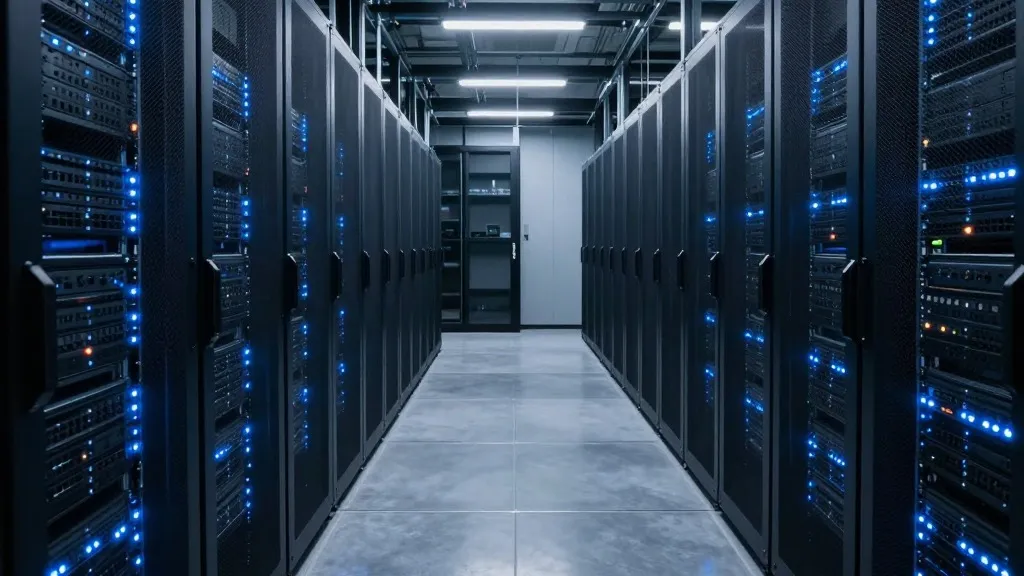
During the earnings call, CEO Elon Musk and CFO Bret Johnsen provided guidance that further fueled investor optimism. They outlined first-quarter 2027 revenue projections between $33 billion and $37 billion, a figure significantly higher than the approximately $22 billion previously modeled by analysts. Management also detailed fourth-quarter capital expenditure plans ranging from $35 billion to $40 billion, primarily focused on AI compute infrastructure at sites in Memphis and Southaven. Musk highlighted relentless demand from hyperscalers, noting that compute pricing supports payback periods of less than a year, and potentially as short as six months. The company targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end, with pathways to 13 gigawatts or more by the end of 2027.
Analysts responded by aggressively revising their outlooks. JPMorgan more than doubled its price target to $500 from $240, maintaining an Overweight rating. Other notable increases included Cantor Fitzgerald raising its target to $345 from $246, Barclays to $300 from $254, and Wells Fargo to $274 from $214. Citi, UBS, and TD Cowen also raised their targets to $240, $230, and $224, respectively, while Morgan Stanley held its Overweight rating with a $300 target. Clear Street adjusted its target to $248 from $217. These firms broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Beyond the financials, the earnings call highlighted several strategic developments. The company noted recent orbital success with Starship and the deployment of V3 satellites, alongside momentum in Starlink pricing and enterprise services. Rapid adoption of Grok Bot and plans for spectrum expansion were also mentioned. Additionally, management discussed the formation of special committees to explore a possible combination with Tesla. While the financial results and guidance were the primary catalysts for the stock’s movement, these operational highlights underscored the company’s expanding footprint across launch, connectivity, and artificial intelligence.
Despite the enthusiastic reception, questions remain regarding the sustainability of the elevated spending levels. The planned capital expenditures for AI infrastructure represent a significant financial commitment, and while current pricing supports short payback periods, the scale of the investment requires sustained demand. The average analyst price target has moved higher, reflecting greater conviction in SpaceX’s trajectory, but investors will be watching closely to see if the company can maintain this growth momentum while managing its substantial infrastructure costs.
For now, the market has reacted positively to the combination of strong current performance and ambitious future guidance. The shift in price targets signals a broader consensus that SpaceX’s diversification into AI and its continued dominance in satellite connectivity are creating a more robust and resilient business model. As the company moves toward its 2027 capacity targets, the focus will likely remain on execution and the ability to monetize its expanding compute resources efficiently.
Source: Teslarati